
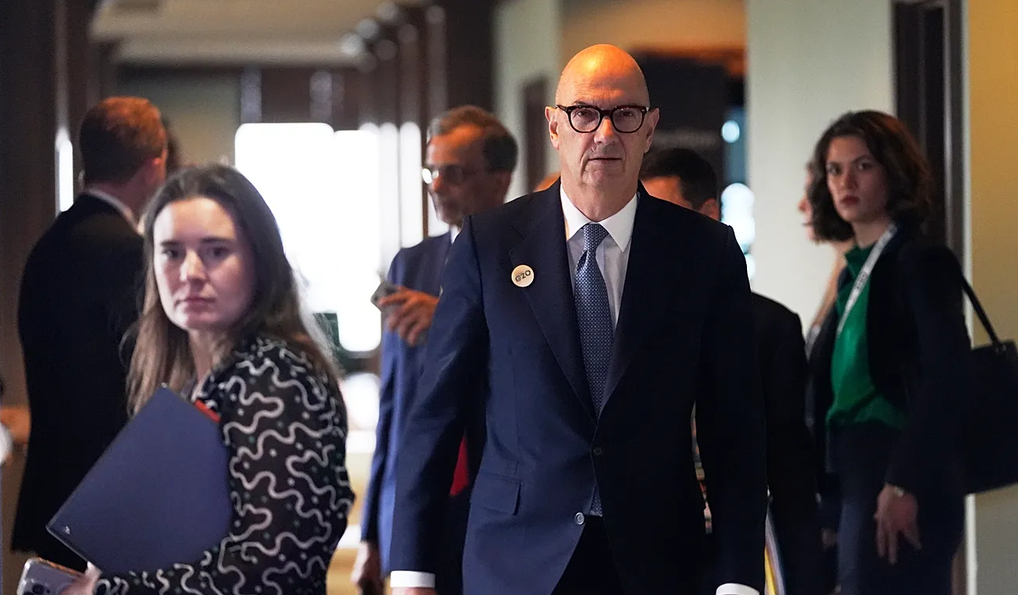
France’s Prime Minister Sébastien Lecornu is set to unveil the country’s 2027 draft budget on Thursday, as his government works to reduce the country’s deficit by cutting public spending.
The broad outlines of many of the government’s budget proposals have already been announced, including savings on pensions, a freeze on public-sector salaries and changes to state-funded sick leave.
The deadline for the formal submission of the 2027 Finance Bill to the National Assembly is 6 October. However, the government faces a challenging political environment in a fragmented parliament without a clear governing majority, which means that pushing its budget through will likely involve difficult negotiations and a potentially arduous parliamentary battle.
“Ultimately, there will be a lot of back and forth between the government, the National Assembly, and the Senate—possibly lasting well into the first half of 2027, and implying more political uncertainty and raising more concerns about the medium-term fiscal outlook,” said Jérémie Peloso, Chief Strategist for Europe at BCA Research.
Key budget proposals
In an interview with Le Figaro on 17 September, Prime Minister Sébastien Lecornu said the government planned cuts of around €54 billion, arguing that, without cost-saving measures, the public deficit could approach 6.5% of GDP in 2027, while the government was targeting a deficit of 5% of GDP.
Lecornu declared that without those cuts, “the 2027 deficit would approach 6.5% of GDP.” The government is also expecting an additional cost of €10bn to finance France’s debt burden.
“Next year, due to the geopolitical context and rising interest rates, the country will need to find an additional 10 billion euros”, he said.
The government is also considering measures to curb the costs of pensions, notably by limiting their indexation and reducing the tax deduction available to retirees. A reduction in the 10% tax deduction ceiling is expected to generate an additional €1.4 billion for the state.
France’s debt reaches record levels
At present, France’s budget deficit is projected to reach 5.4% of GDP this year, one of the largest deficits in the European Union, while public debt is at 119% of GDP.
On Thursday, France’s 10-year borrowing rate climbed to 4.94%, a level last seen in 2002.
The country’s public debt has climbed to record levels during the two terms of President Emmanuel Macron, unsettling investors and emerging as a defining issue ahead of next year’s presidential election.
According to François Facchini, professor of economics at Paris 1 Panthéon-Sorbonne University, the ratio of debt to GDP is expected to climb further.
“The public debt ratio will not fall in 2027, it is expected to climb above 120%,” Facchini told Euronews.
He noted that the standard public debt metric fails to count future liabilities like civil service pensions, meaning it underreports the nation’s true financial obligations.
Jérôme Mathis, professor of economics at Paris-Dauphine University, said the credibility of the government’s deficit reduction plans would hinge on three factors: whether the €54 billion in proposed savings could be sustained, whether the deficit excluding debt interest payments would improve, and whether the economic forecasts underpinning the budget were realistic.
“A budget is only credible if its foundations are credible,” he told Euronews.


Leave a comment